Investment performance is easy to focus on because it produces numbers that can be measured and compared. An account balance can be checked, a portfolio can be reviewed, and returns can be tracked over time.
But long-term financial security involves much more than how an investment account performs.
Retirement income, taxes, cash flow, insurance, estate planning, family priorities, investment time horizons, and changing life circumstances can all affect whether someone is prepared for the future. A portfolio is an important component of that picture, but it is not the entire picture.
For investors thinking beyond the next market cycle, the more useful question may be whether their overall financial strategy is designed around the life they want to fund.
A Portfolio Is Only One Part of the Picture
A portfolio exists for a purpose. For one investor, that purpose may be retirement. For another, it could be funding education, purchasing property, creating future income, preserving wealth, or leaving assets to family.
Those different objectives can influence how an investor thinks about time horizon, liquidity, risk, and the role of different assets.
This is why a portfolio should generally be viewed in the context of the rest of the financial picture.
Someone approaching retirement may have investments, a pension, government benefits, real estate, cash reserves, and other assets. Someone earlier in their career may have a longer investment horizon but also have a mortgage, children, business interests, or other competing financial priorities.
The portfolio cannot be evaluated properly without understanding what it is expected to accomplish.
A broader planning process can help connect those individual pieces. Exponent Investment Management works with professionals, business owners, and families on wealth management and financial planning, illustrating how investment decisions can be considered alongside broader financial objectives.
Define the Goals Behind the Investments
Before focusing on performance, investors can consider what their money is ultimately meant to achieve.
A long-term financial plan may involve several goals at different stages. Retirement might be the largest, but it may not be the only one.
For example, an investor could want to:
- Maintain a particular lifestyle after leaving work
- Help children or grandchildren financially
- Purchase or renovate a property
- Build a financial reserve for unexpected needs
- Support charitable causes
- Preserve assets for future generations
These goals may have different timelines.
Money needed within a relatively short period may need to be treated differently from money intended to remain invested for decades. Likewise, someone with substantial future income may have different financial priorities from someone already relying heavily on investment income.
The Government of Canada’s financial-planning guidance describes financial planning as a way to connect current resources with short- and long-term life goals and emphasizes that a plan should be updated as circumstances change.
The practical lesson is straightforward: investments should have a job, and that job should be connected to the investor’s broader financial objectives.
Consider Income Needs
Accumulating assets and generating income are not necessarily the same challenge.
During working years, an investor may be focused primarily on building wealth. Later, the focus can shift toward how assets will support regular spending.
Retirement planning therefore requires more than estimating a future portfolio value. It also involves considering expected expenses, other sources of income, the timing of retirement, and how long assets may need to support the investor.
Canadian retirement planning resources identify sources such as public pensions, workplace pensions, personal savings, and investments as potential components of retirement income.
The exact mix varies from person to person.
An investor may also have income from rental property, a business, consulting work, or other sources. These can change over time, making it useful to review the complete income picture rather than evaluating investments independently.
A strong financial plan can help an investor think about how assets and income sources work together rather than treating the investment portfolio as the sole source of future security.
Think About Taxes and Estate Planning
Investment decisions can have consequences beyond investment performance.
Taxes may affect how much of an investment return is ultimately available for spending or reinvestment. The type of account, income generated, timing of transactions, and an investor’s broader financial circumstances can all matter.
Estate planning adds another layer.
Investors may want to provide for a spouse, children, grandchildren, or charitable organizations. They may also own real estate, private businesses, insurance policies, registered accounts, or other assets that need to be considered as part of the overall estate.
A financial plan can help identify these connections, while qualified tax and legal professionals can provide advice on the specific rules and documents that apply.
This is particularly important when an investor’s financial arrangements become more complex. A portfolio may be performing as expected, but that does not necessarily mean the investor’s estate or tax strategy is aligned with their wider objectives.
Understand Risk in Context
Investment risk is often discussed in terms of market volatility, but financial risk can take several forms.
An investor may face the risk of needing money at an inconvenient time, depending too heavily on one asset, having insufficient liquidity, or being unable to maintain a desired lifestyle after retirement.
Diversification can be one part of managing concentration, but the appropriate approach depends on the investor’s circumstances and objectives.
Risk should also be considered in relation to time horizon.
A temporary market decline may have a different significance for someone investing for several decades than for someone who expects to draw heavily from their portfolio in the near future.
This is one reason portfolio performance should be interpreted rather than viewed in isolation.
A strong return during one period does not automatically mean a portfolio is appropriate for a particular investor. Likewise, a weaker period does not necessarily mean a long-term strategy has failed.
The relevant question is how the investment strategy fits the purpose of the money.
Review the Plan as Circumstances Change
A financial plan should not remain unchanged simply because the original investments are still in place.
Careers change. Families grow. Businesses are sold or acquired. People move. Retirement dates shift. Spending priorities evolve. Major assets may be purchased or sold.
Each change can affect the broader financial picture.
For example, someone who changes careers may have a different income trajectory. A business owner preparing for a future sale may need to reconsider how much wealth remains concentrated in the company. A person approaching retirement may need to review income requirements and liquidity.
These changes do not automatically mean an investor should make dramatic portfolio adjustments. They do mean the underlying financial plan may deserve another look.
Regular reviews can help determine whether the goals, assumptions, time horizons, and investment strategy still fit together.
Look Beyond the Performance Number
Investment performance will always matter. It is reasonable for investors to want to know how their assets are performing.
But performance is only one measure within a much larger financial picture.
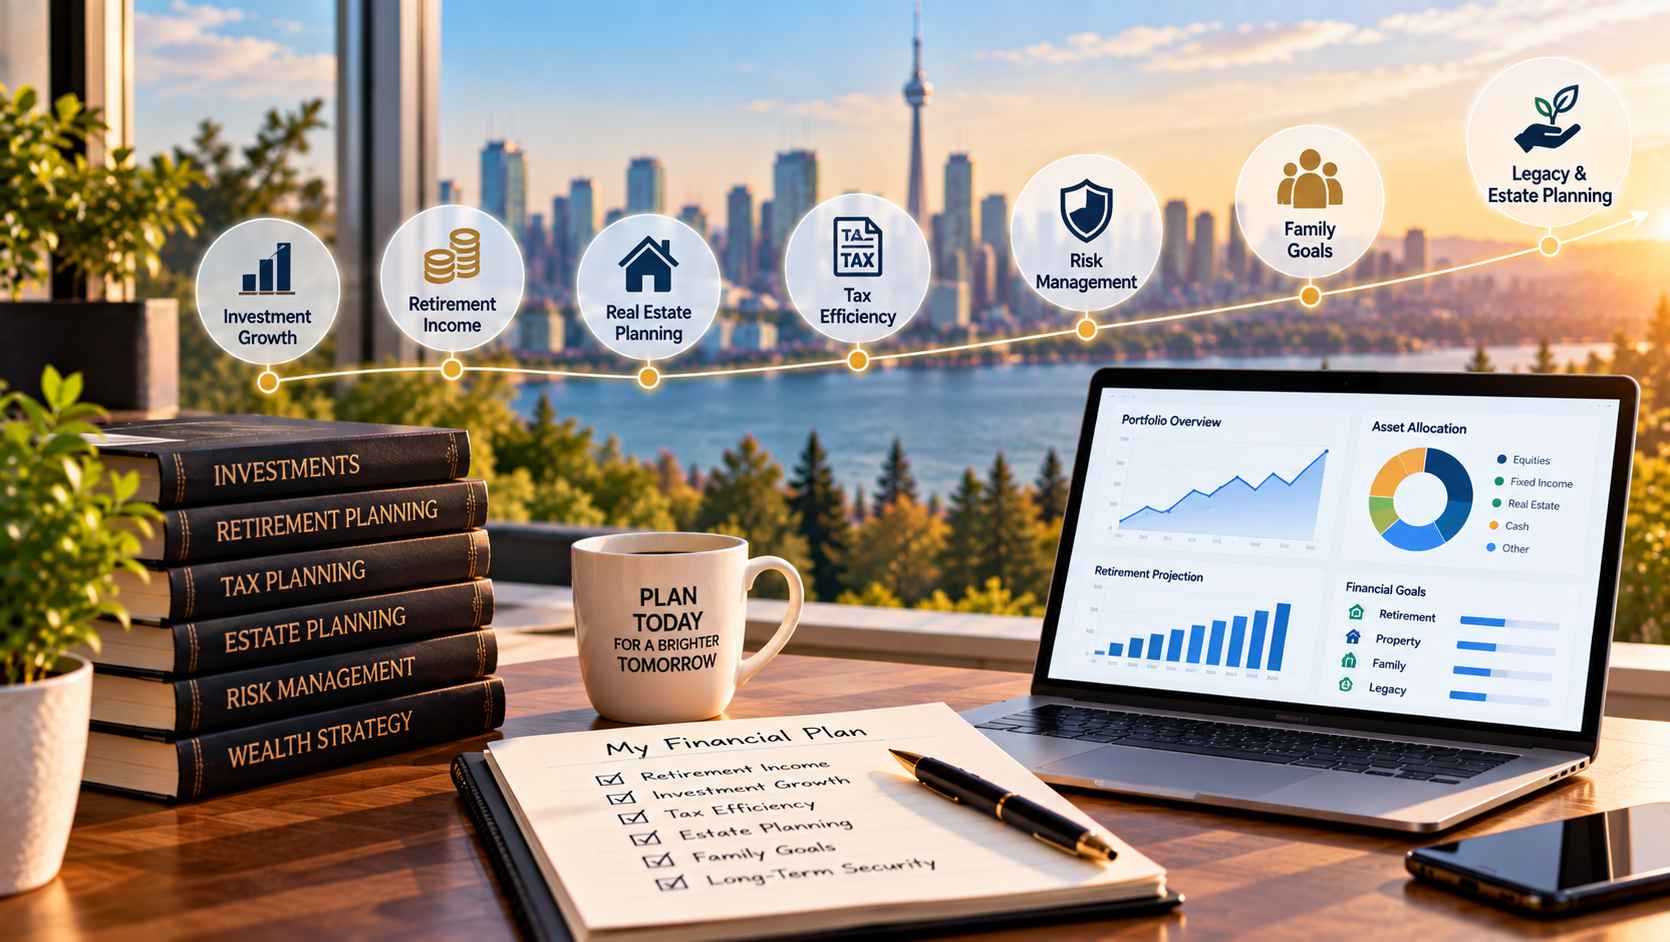
Long-term financial security depends on how investments interact with retirement income, taxes, estate objectives, family needs, cash flow, risk management, and future goals.
A portfolio that is evaluated only by its latest return can miss those connections.
Comprehensive wealth planning can provide a broader framework for considering investments alongside the other financial decisions that shape an investor’s future.
The goal is not to predict exactly what markets will do or eliminate every uncertainty. It is to make sure the financial strategy has a clear purpose and remains connected to the investor’s changing circumstances.
For long-term investors, that broader perspective can be more meaningful than any single performance figure. A portfolio is a tool for building and managing wealth; a financial plan helps determine what that wealth is ultimately intended to accomplish.